
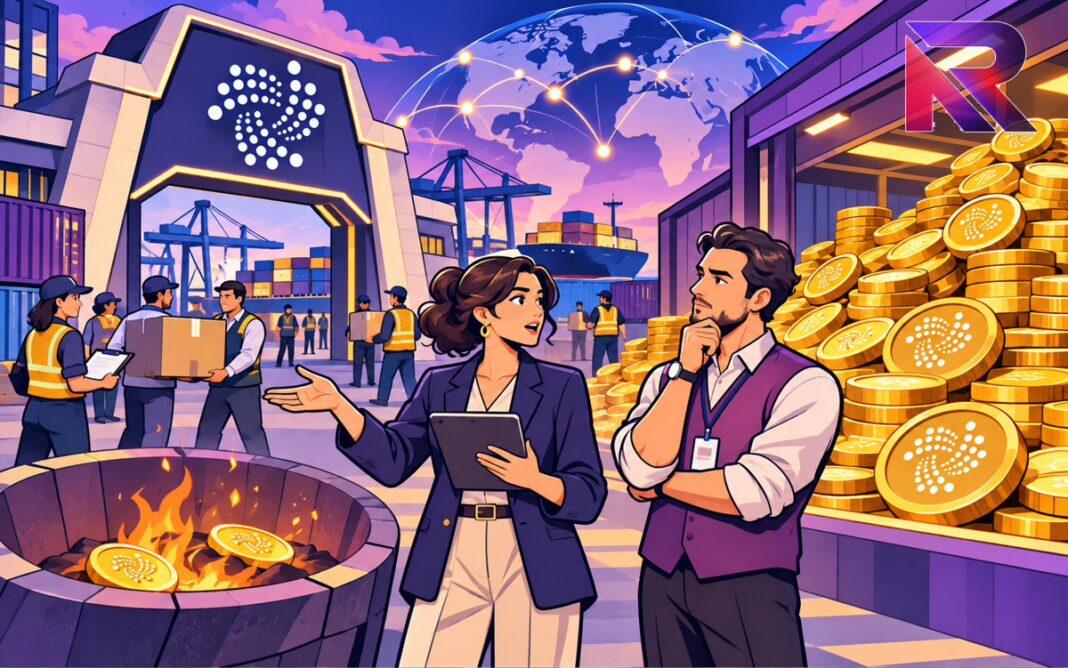
Imagine taking one out of every hundred international shipments, moving its paperwork onto a blockchain, and generating 650 million transactions a year.
That’s the scenario IOTA has presented for its global trade ambitions.
For a network hoping to turn customs documents, digital identities, and shipping records into everyday blockchain activity, the number sounds enormous. And according to IOTA’s own economic narrative, greater adoption should eventually make its token scarcer.
But there’s a rather inconvenient number sitting on the other side of that equation.
Every day, IOTA creates 767,000 new tokens to reward network participants.
At the average transaction burn measured in a recent network epoch, those hypothetical 650 million annual trade transactions would destroy only about 1.29 million IOTA.
That’s less than half a percent of the network’s modeled annual issuance.
The arithmetic doesn’t invalidate IOTA’s ambitions. It does, however, expose a gap between putting global trade on-chain and making the token economy genuinely deflationary.
And that gap becomes considerably more interesting when we examine what the blockchain is already recording.
The 650 Million Transactions Behind IOTA’s Scarcity Pitch
In his January 22 manifesto, IOTA co-founder Dominik Schiener outlined an ambitious plan to position the network as infrastructure for a global trade economy worth tens of trillions of dollars.
Rather than competing solely for cryptocurrency traders, IOTA wants to digitize the documents, identities, and financial instruments involved in moving goods across borders.
The manifesto estimates that 2.5 billion consignments move internationally each year.
Based on IOTA’s work with customers, each consignment could generate an average of 26 blockchain transactions, including document creation, shipment updates, and records of important events.
Digitize just 1% of those consignments, and the calculation becomes straightforward.
Twenty-five million shipments multiplied by 26 transactions produces 650 million annual mainnet transactions.
The manifesto connects that potential activity directly to token economics.
It describes IOTA’s economy as “deflationary by design,” arguing that transaction fees destroy tokens while storage deposits temporarily or permanently remove them from available circulation.
The underlying proposition is appealing: more trade creates more blockchain activity, which creates more demand for network resources and stronger scarcity pressure.
But 650 million transactions is a scenario, not a measured annual trade volume already running through IOTA.
And even if that scenario materializes, the amount of IOTA destroyed depends on what those transactions actually cost.
That distinction changes the calculation.
IOTA Minted 767,000 Tokens While Burning Just 1,161
IOTA’s technical and tokenomics whitepaper, published in May 2025, explains that the Rebased network introduced a fixed daily staking subsidy.
At the end of each roughly 24-hour epoch, the system can distribute 767,000 newly created IOTA among validators and delegators.
Transaction fees work in the opposite direction. They burn tokens, reducing total supply.
The network can therefore experience either net inflation or net deflation depending on the balance between issuance and burning.
For epoch 552, completed around November 9, the community-operated PULSE analytics dashboard reported the following:
| Metric | Epoch 552 |
|---|---|
| Newly minted IOTA | 767,000 |
| IOTA burned through gas | 1,161 |
| Net supply increase | 765,839 |
| Burn as a share of issuance | 0.151% |
For every IOTA destroyed through transaction fees, roughly 661 new tokens entered the supply.
That’s not a particularly close contest.
The same dashboard recorded about 2.47 million total transactions during the epoch, but estimated only around 582,000 fee-paying transactions for its burn-efficiency calculation.
That distinction matters because a large transaction count does not necessarily translate into equally large fee consumption.
Ravel has not independently reconciled PULSE’s epoch 552 burn figures against the raw checkpoint records. They should be treated as dashboard-reported measurements rather than a separately audited transaction reconstruction.
Still, the broader direction is supported by other historical records. IOTA’s official explorer shows that epoch 517 minted 767,000 tokens while burning fewer than 184.
More importantly, the official IOTA Explorer recorded a total supply of approximately 5.023 billion IOTA around epoch 552.
The Rebased network began in May 2025 with 4.6 billion.
That’s a net increase of roughly 423.28 million IOTA, or 9.2%, since launch.
It measures growth in total supply, not tokens newly released onto exchanges or currently available for trading.
But the direction is unambiguous: IOTA’s total token supply has been expanding, not contracting.
What Would 650 Million Trade Transactions Actually Burn?
Now comes the test.
PULSE estimated an average burning of roughly 0.00199 IOTA per fee-paying transaction during epoch 552.
Suppose IOTA achieves the manifesto’s 650 million annual trade transactions, every one generates a fee-paying operation, and the average burn remains unchanged.
Ravel calculates:
650 million transactions × 0.00199 IOTA = 1.2935 million IOTA burned annually.
Compare that with the network’s issuance schedule.
At 767,000 IOTA per epoch, 365 epochs would create 279.955 million tokens before accounting for burns.
The hypothetical trade activity would offset just 0.46% of that annual issuance.
The gap becomes clearer when testing larger adoption scenarios.
| Share of global consignments digitized | Annual transactions | Estimated annual fee burn |
|---|---|---|
| 1% | 650 million | 1.29 million IOTA |
| 10% | 6.5 billion | 12.94 million IOTA |
| 100% | 65 billion | 129.35 million IOTA |
These are Ravel’s calculations using the manifesto’s 26-transaction assumption, the epoch 552 fee-paying burn estimate, and unchanged network economics. They are illustrative scenarios, not adoption forecasts.
Even if every international consignment in IOTA’s model generated those 26 transactions, annual fee burning would offset only about 46.2% of the assumed issuance.
That doesn’t mean the network must capture more than the entire global shipping market to become deflationary. Other applications can generate transactions, and the fees themselves can change.
But it tells us something important about the trade narrative.
At the measured fee level, trade documentation alone is unlikely to neutralize issuance simply by reaching the manifesto’s initial adoption target.
In fact, for 650 million annual fee-paying transactions to fully offset 279.955 million newly minted IOTA, the average burn would need to reach roughly 0.4307 IOTA per transaction.
That’s about 216 times the measured average.
Alternatively, keeping the burn at 0.00199 IOTA would require roughly 140.7 billion fee-paying transactions annually to offset the same issuance.
Neither requirement is a prediction. Both simply establish what the existing arithmetic implies.
And both change if transaction costs, execution complexity, issuance rules, or the mix of network applications change.
The Difference Between Burning Tokens and Locking Them
There is an important counterargument to all this.
IOTA’s economic model does not depend on transaction burning alone.
The manifesto also emphasizes staking and storage deposits, which can reduce the quantity of tokens immediately available to market participants.
When users create certain on-chain objects, they may need to lock IOTA as a storage deposit. Those tokens can become available again if the associated storage obligation is released.
That’s fundamentally different from permanently destroying tokens.
Staking creates another form of restricted availability. Delegated IOTA helps secure the network, although staking doesn’t remove those tokens from total supply.
And circulating supply introduces another complication.
IOTA’s whitepaper identifies a scheduled token-unlocking process that extends into 2027. Previously locked allocations can become available even while other holders increase their staking commitments.
The network can therefore experience rising total supply, changing market circulation, and increasing temporarily locked balances at the same time.
None of those measurements should be treated as interchangeable.
PULSE, for example, excludes staked and storage-locked tokens from its available-supply metric, while the official explorer reports a different circulating-supply figure.
Those figures answer different questions about token availability.
To test the manifesto’s broader scarcity thesis, the relevant evidence would need to include fee burning, newly issued rewards, storage deposits and their releases, staking behavior, and scheduled unlocks over time.
The current fee data settles only part of that argument.
But it’s an economically significant part.
Because fees permanently destroy tokens, while many other restrictions merely postpone when holders can use them.
IOTA’s Trade Ambitions Still Have a Real Economic Case
None of this means IOTA’s trade strategy lacks commercial substance.
Digitizing shipping documents, improving verification, and reducing reconciliation costs could create legitimate demand for blockchain infrastructure.
The ecosystem is already pursuing that direction.
As Ravel reported in its examination of the Sweden–Estonia freight pilot, European partners are testing IOTA-linked TWIN infrastructure for cross-border transport documentation.
The pilot offers an example of the kind of institutional workflow IOTA hopes to capture.
What remains less clear is how much activity from such projects ultimately settles on the public mainnet, what transaction costs it generates, and how many tokens become locked for storage.
Those are questions about measurable economic usage rather than the number of partnerships.
There’s also a reason not to dismiss the network’s staking emissions as inherently wasteful.
Newly minted tokens compensate participants securing the blockchain. Reducing issuance may improve supply economics for existing holders, but it can also affect incentives for validators and delegators.
Ravel explored a similar trade-off in its investigation of NEAR’s proposed issuance reduction, where lower inflation raised uncomfortable questions about validator sustainability.
IOTA faces a different version of that challenge.
Its fixed token issuance supports network security, while greater economic activity is supposed to offset dilution through burning and token demand.
The design is coherent.
Whether adoption eventually generates enough sustained economic pressure to change the supply trajectory is a separate question.
The Scarcity Story Still Needs Its Numbers
IOTA has never hidden the existence of token issuance.
Its whitepaper explicitly explains the daily subsidy, the uncapped total supply, and the mechanisms intended to counterbalance inflation.
The issue is not undisclosed token creation.
It’s the distance between the economic destination described in the manifesto and the results visible today.
At the measured epoch 552 burn rate, the network destroyed only 0.151% of the tokens created that day.
Its total supply has increased by more than 423 million tokens since Rebased launched.
And even the manifesto’s headline scenario of 650 million annual trade transactions would offset less than 1% of annual issuance through transaction burns at the measured fee level.
Those numbers don’t rule out future deflation. Higher-value transactions, additional applications, changing fees, and sustained storage demand could materially alter the economics.
They do, however, establish what IOTA must eventually demonstrate.
More blockchain activity is not automatically the same thing as a shrinking token supply.
More documents, shipments, and transactions may build a valuable network. Whether they create meaningful scarcity depends on how much IOTA those activities consume or keep unavailable relative to issuance.
IOTA has described the economic destination.
The blockchain is still showing how far away it is.